The Legacy Minded Parent
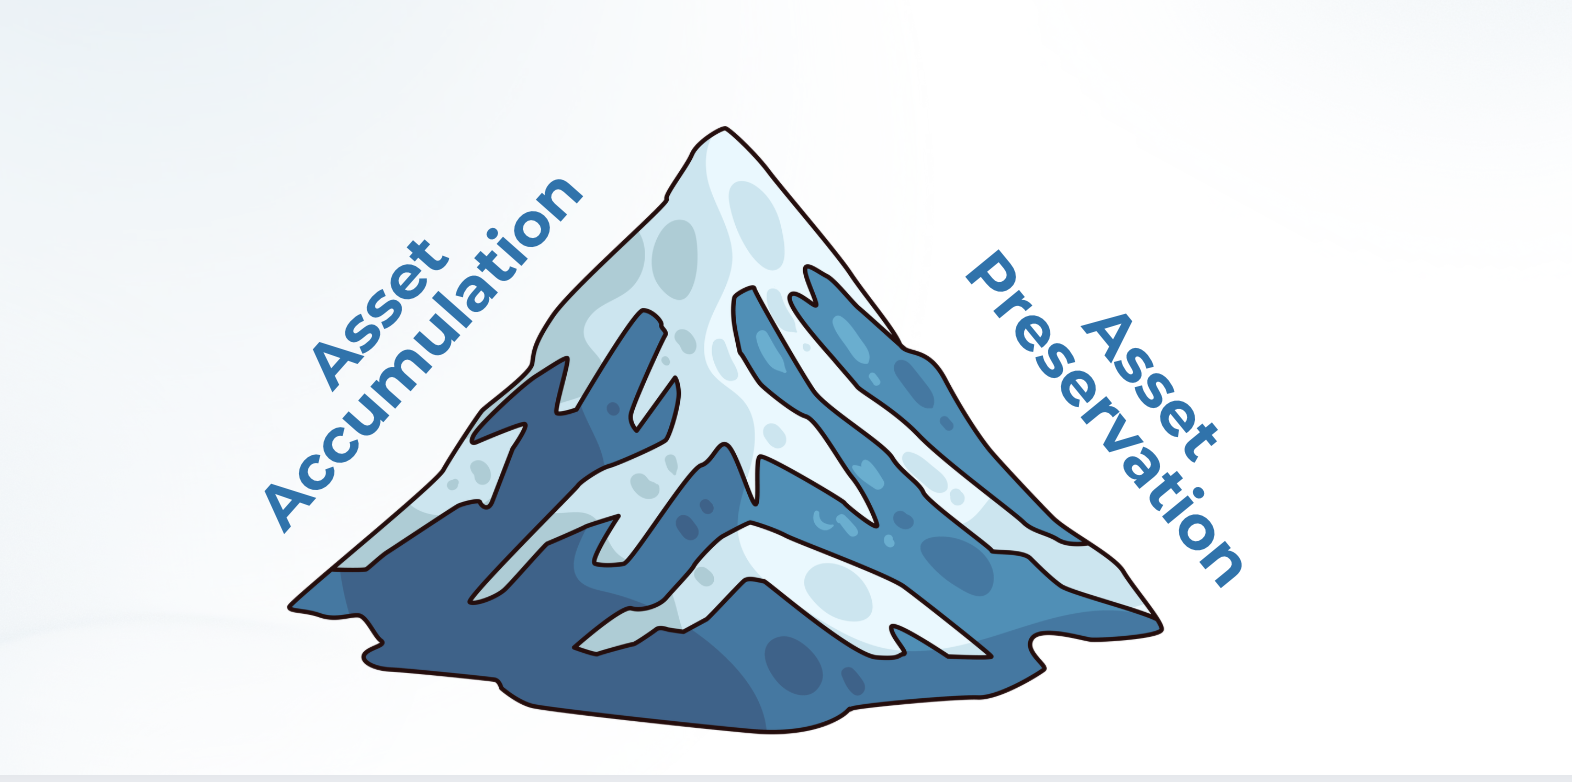
You spent thirty years learning how to climb. Nobody ever taught you how to come down.
Ask any mountaineer where the accidents happen. It is almost never on the way up. Going up is asset accumulation and you have already proven you can do it. Going down is asset preservation, and it is a completely different skill with completely different rules.
The Pill Formula
Four questions decide whether your money survives the descent.
Not one of them is about picking a better fund.
Principal Protection
How do I make sure my money is protected from the downside of the market?
A thirty percent loss at thirty two is an inconvenience. The same loss at sixty two is a different life. You are no longer investing on a timeline where the market gets to be wrong for a few years.
Income For Life
How much monthly income do I need to never have to work again, and what happens if I outlive the money?
A balance is not an income. Most people can tell you what they have saved. Very few can tell you what it pays them per month, for how long, and what happens in year thirty one.
Long Term Care
If I need care for years, does it come out of my retirement, or out of my children's?
Most of us have watched a grandparent get moved into a facility and watched a lifetime of savings get spent down to qualify for help. That was not bad planning. It was no planning, because nobody warned them it was coming.
Legacy
Either you need life insurance and do not have it, or you have it and do not need it. Which position do you want to be in?
This is the only decision on the list where being wrong is permanent, and the only one that gets more expensive every year you wait.
What You Were Told
Four things almost everyone believes, and all four are out of date.
The Myth
Retirement is the goal.
The Reality
Retirement as a life stage is barely a hundred years old. It was invented by governments and corporations, not by scripture and not by anyone thinking about your purpose. Numbers 8 describes the Levites stepping back from regular service at fifty and continuing to serve in a different role. Not stopping. Shifting. The goal was never to stop working. The goal is to reach the point where work becomes a choice. That is not retirement. That is financial independence.
The Myth
The four percent rule will keep me safe.
The Reality
The four percent rule is a probability, not a promise. It was built on a fixed thirty year window and it assumes you can sit still while your portfolio drops. Its biggest weakness is timing. If the market falls hard in your first few years of withdrawals, you are selling shares at a loss to pay your bills, and the math never recovers. Same average return, completely different outcome, decided entirely by what order the years arrive in. You do not get to choose that order.
The Myth
Social Security, my pension, and my retirement plan will carry me.
The Reality
That was the three legged stool, and it worked. The problem is that two of the legs have quietly been removed. Traditional pensions have all but disappeared from private employers, replaced by a plan where the employee carries all the risk. Social Security remains, but it was designed as a supplement, never as the floor. The stool did not break. It was redesigned, and nobody sent you the notice.
The Myth
A 401k is the only way.
The Reality
It is one way, and most people have never actually read theirs. Ask yourself four questions. Do you know your vesting schedule, and what you forfeit if you leave early? Do you know what a target date fund does to your allocation as you age, and whether you agree with it? Do you know the difference between the moderate and aggressive options you selected once and never revisited? And do you know that fifty nine and a half is not the only door, because there are provisions that allow earlier access without the penalty in specific situations? Most people answer no four times. That is not a failure. Nobody ever handed them the manual.
What We Actually Build
Six moves that change the descent.
Which ones apply to you depends entirely on your situation. That is the point of the conversation.
Protect The Principal
Position a portion of your money where a bad year in the market does not become a bad decade in your life.
Build Income You Cannot Outlive
Turn a balance into a monthly number that keeps arriving, structured so longevity becomes a blessing instead of a risk.
Open The Door Before 59 And A Half
There are specific provisions that allow access to retirement funds earlier than most people believe, without the early withdrawal penalty, when the situation qualifies.
Build A Private Pension
Employers stopped offering pensions. That does not mean you cannot build one. It means you have to build it yourself, on purpose.
Cover The Care
Structure coverage so a long term care event is handled by a plan instead of by your retirement account or your children.
Protect What You Own
Titling, beneficiaries, and structure reviewed so that what you built actually reaches the people you built it for.
The Four Necessities
Four documents. Most families have one, and it is usually the wrong one.
These are not about money. These are about what happens on the worst day, when nobody in your family is thinking clearly and every decision is urgent.
A Trust
Keeps your estate out of probate, so what you leave transfers privately and directly instead of being frozen in a public court process for months.
Do your assets move to your family, or to a courtroom first?
A Will
Directs who receives what, and names a guardian for anyone who depends on you. Pair it with a letter of instruction, which is not legally binding but tells your family the things a legal document never captures.
If you were gone tomorrow, would your family know what you wanted, or would they be guessing?
Financial Power Of Attorney
Names the person who can handle your money if you are alive but unable to manage it yourself.
Who do you trust with your finances on the day you cannot manage them?
Healthcare Proxy
Names the person who makes medical decisions on your behalf when you cannot make them yourself, and records what you would want.
Have you told that person, or are you assuming they already know?
Estate documents are prepared by a licensed attorney. My role is making sure they exist, that they match your financial plan, and that they are actually funded.
The climb is behind you. The descent is the part that decides everything.
In one sitting we walk the four PILL questions, look at what you actually have, and identify which moves fit your situation.